
Why funding is so important in care
Care is not just a medical or organisational issue. It is almost always a financial issue as well. As soon as a person needs regular support, costs arise: for domestic help, home care, personal care, care aids, transport, home adaptations, day care, short-term care or, later on, perhaps for a care home. Many families only realise, as they go about their daily lives, just how many small and large expenses add up. A single bill can quickly become an ongoing budgetary concern.
Long-term care insurance is designed to provide relief in precisely these situations. However, it does not automatically cover everything, nor does it replace comprehensive insurance. Anyone organising care must therefore understand which benefit is suitable for which situation. Care allowance is more suitable for home care provided by relatives. Care benefits in kind apply when an outpatient care service is involved. The relief allowance supports everyday assistance and care. Grants for home adaptations can reduce barriers within the home. In-residence care services provide support in a care home, but often do not cover all costs.
The real difficulty lies in the fact that these benefits co-exist and can, in some cases, be combined. This is precisely where the multi-act German administrative saga begins: submitting an application, gathering supporting documents, checking the decision, noting the deadline for appeal, submitting the invoice and hoping that nobody misses a tick in field 7b of the form. Nevertheless, it is worth the effort, as unused benefits mean a loss of financial support in day-to-day care, less relief and often more stress for relatives.
Good financial planning therefore does not begin with the care home contract. It begins as soon as the first limitations in everyday life arise. Those who check early on what entitlements they have can make better use of benefits, compare suitable providers and apply for any necessary adjustments in good time. The care level is particularly important here, as it determines which forms of financial assistance are actually available.
Long-term care insurance as a key pillar
Social care insurance is the most important pillar of care funding in Germany. It supports people in need of care with fixed benefits, which are graded according to care level and type of care provided. Among other things, it distinguishes between home care, professional outpatient care, semi-residential care and residential care. The level of benefit therefore depends not only on the extent of a person’s disability, but also on where and by whom the care is provided.
It is important to note that long-term care insurance is intended as partial cover. It reduces costs but does not cover every bill in full. This can be a sobering realisation for many people affected at first. In the case of care homes in particular, there is often a co-payment to be made. Outpatient care can also become more expensive if more services are required than the long-term care insurance fund’s budget covers. Therefore, care insurance should not be seen as covering all costs, but rather as a basic financial framework.
For those with statutory health insurance, the care insurance scheme is administered by the relevant health insurance provider. Those with private insurance should contact their private compulsory long-term care insurer. The first practical step is almost always to apply for a care level assessment. The Medical Service – or, for those with private insurance, Medicproof – then assesses how independently the person concerned can still manage their daily life. This assessment results in a classification into care levels 1 to 5.
Many families underestimate the importance of this assessment appointment. Someone who appears as capable as possible on a good day may, under certain circumstances, receive a lower assessment than their actual day-to-day needs warrant. What matters is not the impression made on a single morning, but the regular need for support. It is therefore a good idea to keep a care diary in which assistance provided, night-time disturbances, mobility problems, cognitive limitations and the organisational effort involved are documented.
Care levels: The key to benefits and grants
The care level is the key factor in care funding. It describes the extent to which a person’s independence is impaired. Unlike in the past, the focus is no longer solely on the time required for individual care tasks, but rather on the question of which areas of life require support. The assessment covers mobility, cognitive and communicative abilities, behaviour, self-care, coping with illness-related demands and the organisation of daily life.
Care Level 1 indicates a minor impairment of independence. At this stage, there is no care allowance and no regular care benefits in kind, but important forms of support are already available, such as the respite allowance, advice and grants for home adaptations. From care level 2 onwards, the benefits become significantly more comprehensive. These include a care allowance, care benefits in kind, respite care, short-term care and further support.
This assessment is crucial for funding, as almost every benefit is linked to the care level. A higher care level generally means higher benefit payments, but also a greater recognised need for support. That is why a decision notice should be checked carefully. If the assessment does not reflect the reality of daily life, it may be worth lodging an appeal. Many people shy away from this because ‘appeal’ sounds like a hassle. In fact, it is a standard legal remedy and not a declaration of war on the long-term care insurance fund, even if the pile of paperwork occasionally seems to suggest otherwise.
It is particularly important that relatives do not downplay the actual burden involved. Many care situations are treated as normal out of habit. If someone helps with washing every day, prepares medication, serves meals, coordinates appointments and gets up several times during the night, that is by no means ‘just a bit of support’. It is care work. It is precisely this reality that must be reflected in the application and during the assessment.
- Care Level 1: Initial support services, relief allowance and advice.
- Care levels 2 to 5: care allowance, benefits in kind and many other entitlement to benefits.
- Appeal: This is advisable if the assessment does not realistically reflect the actual care needs.
Care allowance: Financial assistance for care provided by relatives
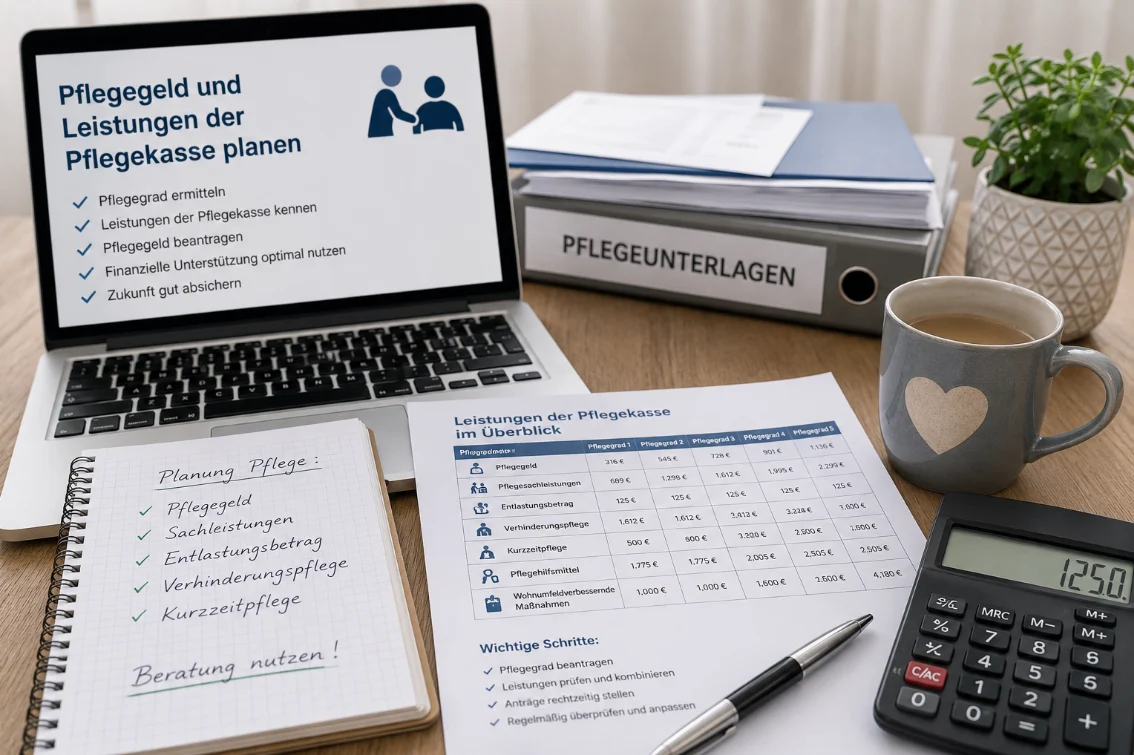
People in need of care from care level 2 onwards are entitled to a care allowance if their care at home is organised by themselves. This usually means that relatives, friends or other trusted individuals provide regular support. The long-term care insurance fund pays the care allowance directly to the person in need of care. They are free to decide how the money is used. It is often passed on to family carers in recognition of their efforts.
Care allowance is particularly important because, in Germany, home care is largely provided by family members. This work is often unseen. It doesn’t just begin with showering or getting dressed, but with the entire organisation of the day: medication, doctor’s appointments, housework, shopping, dealing with health insurance providers, transport, crises, falls, reminders, motivation and emotional support. A carer’s family calendar sometimes looks like a project management tool, only without a pay rise and with more washing up.
The care allowance can help to alleviate this financial burden, at least in part. It does not replace an income and does not cover the cost of full-time care. But it does provide some breathing space. Families can use it to organise additional help, cover travel costs or support family carers. It is important to note that, where care allowance is the sole form of support, regular advisory visits are mandatory. These are intended to ensure the quality of home care and to advise family members.
Care allowance does not have to be used on its own. It can be combined with care benefits in kind. This is referred to as a combined benefit. If an outpatient care service uses only part of the budget, a proportion of the care allowance may remain. This model makes sense in many households because it allows professional support and family care to be combined flexibly.
Care benefits in kind: When the home care service provides support
Care benefits in kind are benefits for professional home care. Unlike with the care allowance, the money is not paid to the person in need of care; instead, the care service settles accounts directly with the long-term care insurance fund. Typical services include assistance with personal hygiene, help with dressing and undressing, mobility support, nutrition, nursing care and certain domestic tasks, provided these are included in the catalogue of services.
Home care services are a vital component for many families, as they provide expertise, experience and reliability. They can take the strain off family carers and help make it possible to provide care at home for longer. At the same time, it is essential to plan carefully which care visits are truly necessary. Care time is limited, costs are rising, and not every type of support requested automatically fits within the long-term care insurance fund’s budget.
When choosing a care service, price should not be the only consideration. Key factors include availability, reliability, designated points of contact, experience with the specific condition, and transparency regarding billing and proof of services rendered. Relatives should ask for an explanation of which services are covered by the care insurance scheme, which must be paid for privately, and what combination with respite care services is possible.
The combined care package is often a good solution. Under this arrangement, the person in need of care uses part of their care benefits in kind and also receives a proportionate care allowance. For example, a care service might provide assistance in the mornings, whilst relatives help out in the evenings and at weekends. This model is practical because care rarely fits neatly into clear-cut categories. Unfortunately, forms love clear-cut categories. As a result, everyday life regularly shows them the door.
Tax relief: A small benefit with a big impact
The relief allowance is generally available to people with a care level and is intended to make everyday life easier. It can be used for recognised services providing support with everyday life. Depending on the federal state and the provider, these may include care services, assistance with daily activities, help with household tasks or support for family carers. The allowance is not simply paid out freely, but is usually settled through recognised providers for specific purposes.
In practice, the relief amount is surprisingly often not utilised in full. There are many reasons for this: those affected are unaware of it, cannot find an approved provider, do not understand the billing process, or put off dealing with the matter until another year has passed. The result is absurd: families are overburdened, whilst available support options remain unused. Bureaucracy apparently has a knack for disguising help in such a way that you only recognise it after three consultation sessions.
This service can be particularly helpful for people who live at home and need small but regular amounts of support in their daily lives. A home help, an escort to the doctor, care for those with dementia or relief on an hourly basis can make all the difference. For relatives, this means free time, less pressure and, sometimes, simply the chance to go shopping or have a sleep in peace.
It is important that providers are accredited. Which providers are approved depends on the federal state. Long-term care insurance funds, care support centres and regional advice centres can recommend suitable providers. Anyone already using a care service should also enquire there as to whether services can be billed against the respite care allowance.
- The relief amount is earmarked for a specific purpose and is usually settled through approved providers.
- It is particularly suitable for care, domestic help, support with daily living and providing respite for relatives.
- Unused amounts may be carried forward under certain conditions, but this should be checked in good time.
Grants for home adaptations
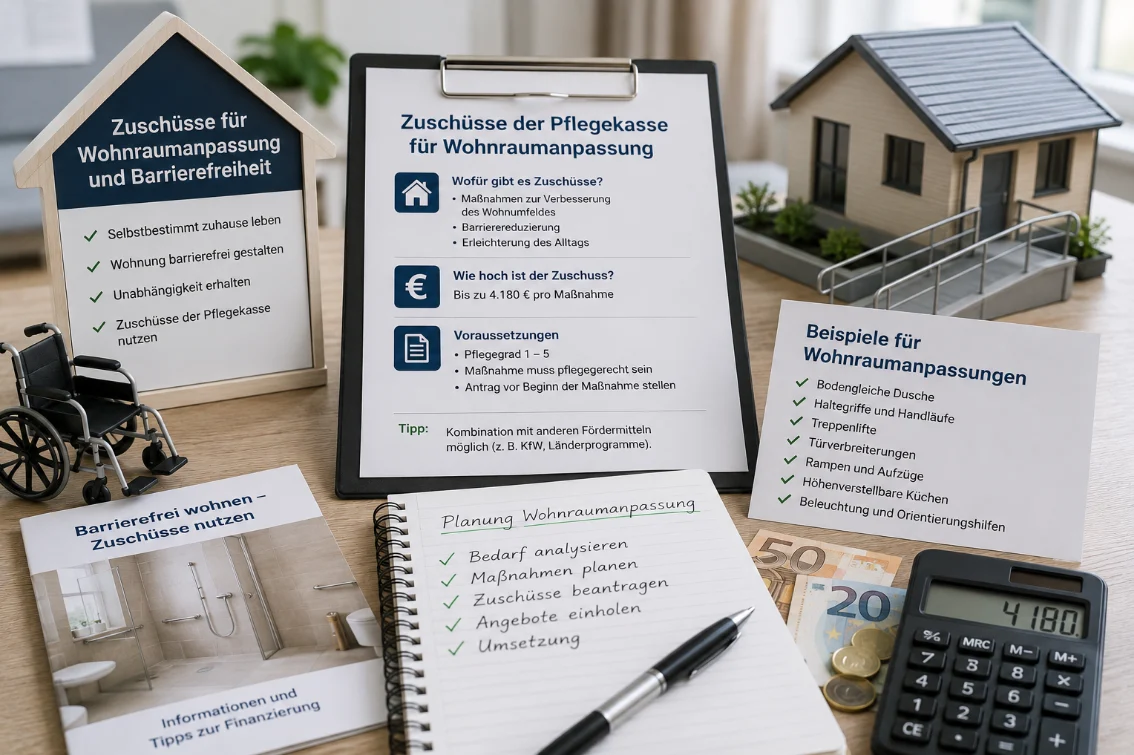
If care is to be provided at home, the home must be suitable for this purpose. This is precisely where things often go wrong. Stairs, cramped bathrooms, high shower trays, thresholds, narrow doors and rooms that are difficult to access suddenly become real obstacles. The long-term care insurance fund may subsidise measures to improve the home environment if this enables or facilitates home care, or if it helps the person in need of care to maintain their independence.
The housing adaptation grant can be used for a wide variety of measures. These include converting to a barrier-free shower, widening doors, installing ramps, fitting permanently installed handrails, making alterations to the entrance area, adapting the bedroom or installing technical solutions such as stairlifts. Even minor modifications can be beneficial if they reduce the risk of falls or make care tasks easier.
The subsidy from the long-term care insurance fund can amount to up to €4,180 per project. It is important that the application is submitted before work begins. Anyone who carries out the alterations first and then asks risks having their application rejected. This is frustrating, but unfortunately typical: help is often available, but only if you apply for it before you urgently need it. People grow older, bathrooms remain impractical, and somewhere, a form is waiting to be filled in.
For major alterations, it is advisable to seek advice from a housing consultant. They can assess which measures are truly worthwhile and which additional funding schemes may be available. Some local authorities, federal states or development banks offer supplementary schemes. KfW grants may also be worth considering, subject to availability. As funding schemes are subject to change, you should always check the current conditions before starting.
Care aids and technical support
Care aids are another important component of funding. They are designed to make care easier, alleviate symptoms or enable a more independent lifestyle. A distinction is made between technical care aids and consumable care aids. Technical aids include, for example, care beds, positioning aids, home emergency call systems or hoists. Consumables include items such as disposable gloves, disinfectants, bed pads or protective aprons.
Consumables, in particular, are needed constantly in everyday life. They may seem like small items, but the costs add up over months and years. The care insurance scheme helps cover these costs with a monthly lump sum, provided the eligibility criteria are met. This is a practical help for families, as it means they do not have to discuss hygiene supplies from scratch every time. However, it is important to check which products are actually needed and whether a supplier offers suitable packages.
Technical care aids can make day-to-day care considerably easier. A care bed not only improves comfort but also protects relatives from physical strain. Lifting aids can make transfers safer. A home emergency call system can provide peace of mind for people living alone. Such aids are not a sign of weakness, but sensible tools. Nobody would run a building site without tools, yet when it comes to care, people try for a surprisingly long time to manage everything with sheer willpower, hope and a lack of sleep.
Whether the long-term care insurance fund or the health insurance fund is responsible depends on the type of aid. Some aids are primarily intended for care, whilst others are for medical treatment or to compensate for a disability. In practice, this distinction is not always immediately clear. Medical supply shops, care services and advice centres can help you choose the right course of action and prepare the necessary prescriptions or applications.
Short-term care and respite care
Short-term care and respite care are among the most important support services for families. They apply in different situations, but are often considered together in everyday life. Short-term care refers to temporary residential care, for example following a hospital stay, after a crisis, or when care at home is temporarily not possible. Respite care comes into play when the private carer is temporarily unavailable, for instance due to illness, holiday or burnout.
These services are hugely important financially, as they can prevent relatives from being pushed to their limits in the long term. Caring for someone at home only works if the carers themselves do not break down. That may sound obvious, but it is surprisingly often ignored. Relatives carry on until they can go no further, and then are surprised that the body is not an operating system with unlimited capacity.
Respite care can be used on an hourly basis or for longer periods. This makes it flexible. A replacement carer can step in, a home care service can take on additional visits, or a care arrangement can be organised. Short-term care, on the other hand, is residential and is particularly suitable for transitional periods. Both services should be planned well in advance, as places and available services can be in short supply.
It is financially worthwhile to examine the available combinations carefully. Under certain conditions, unused funds may be partially carried over or topped up. As amounts and regulations are subject to change, the long-term care insurance fund or advice centre should confirm the current budget available in each specific case. It is crucial that families do not view these benefits as a last-minute stopgap, but as an integral part of good care planning.
Day care and night care
Day care and night care are semi-residential services. The person requiring care continues to live at home but spends certain periods of time in a care facility. In the case of day care, this is usually during the day. Night care can be useful if there is a need for care at night and relatives need some respite. Both services can serve as an important bridge between home care and full-time residential care.
These services are financially attractive because they can be used in addition to care allowance or care benefits in kind. They therefore do not necessarily replace other benefits, but rather supplement the care provided. For relatives, day care can mean being able to return to work, attend appointments or simply have reliable relief for several hours. For those in need of care, it can provide a daily routine, social contact and stimulating activities.
Day care can be particularly valuable for those with dementia, limited mobility or social isolation. These facilities provide meals, supervision, activities and nursing support. At the same time, the person’s home remains the centre of their life. This is important to many people, as moving into a care home permanently can be emotionally difficult.
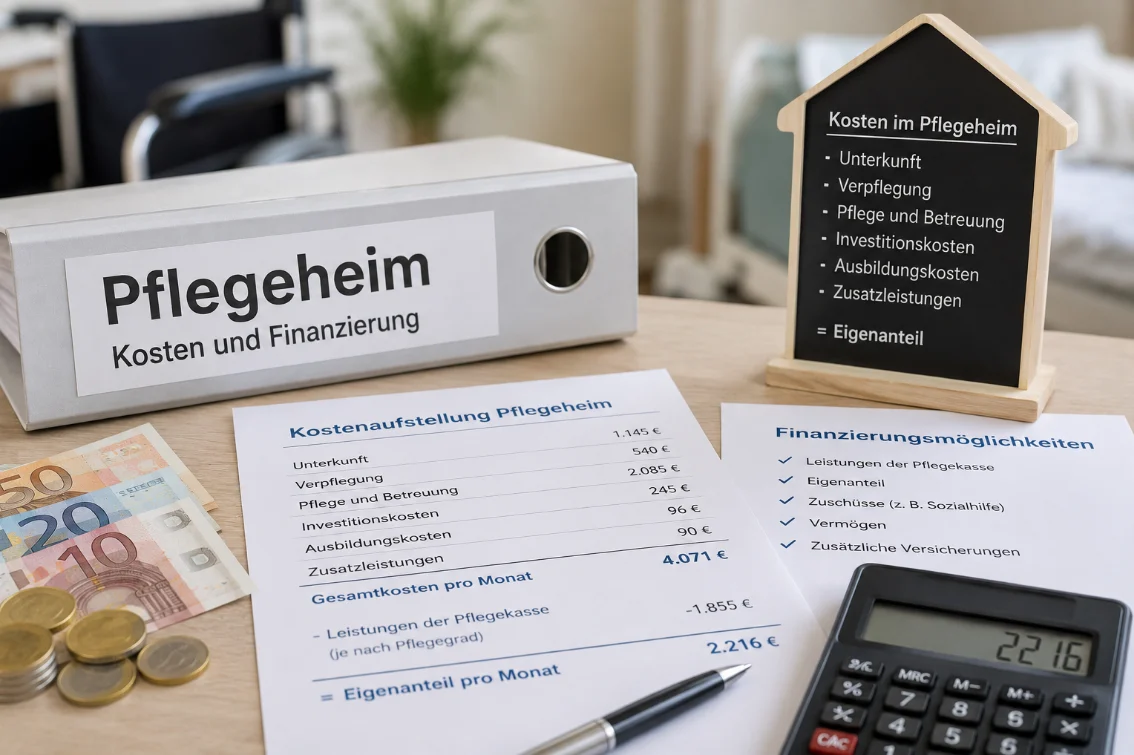
The costs comprise care, support, accommodation, meals, capital expenditure and transport services. Not all of these costs are fully covered. Relatives should therefore enquire in detail before signing a contract to find out which costs are covered by the care insurance scheme and which must be paid privately. Unfortunately, care invoices often appear straightforward at first glance, only to surprise you with footnotes later on.
Funding in care homes
Residential care is often the most expensive aspect of care funding. If care at home is no longer possible or safe, a care home may become necessary. Long-term care insurance contributes towards care-related costs, but does not cover all elements of the care home bill. Accommodation, meals, capital costs and other personal contributions must generally be paid for privately.
The monthly cost can therefore be considerable. Many families are surprised because they assume that a high care level automatically covers most of the care home costs. In fact, there is often a noticeable amount left to be paid by the individual. This is initially covered by the income and assets of the person requiring care. This includes state pensions, private pensions, personal income and existing savings. If this is not sufficient, care assistance from social services may be an option.
When choosing a care home, it is therefore not enough to consider only the location and facilities. What matters are transparent costs, clear contracts, additional services and the question of which services are already included. Investment costs also vary depending on the care home and the federal state. Anyone comparing several care homes should not be dazzled by attractive brochures. Flowers on the cover won’t pay the bill, even if marketing departments would clearly prefer it otherwise.
For several years now, long-term care insurance has been providing supplementary payments towards the care-related personal contribution in full-time residential care homes, which increase with the length of stay. These are intended to ease the financial burden on residents. Nevertheless, personal contributions remain a key issue. It is therefore advisable to seek advice at an early stage, particularly where assets, property, spouses, maintenance payments or social security benefits are involved.
Care support: When income and assets are insufficient
Care allowance is a social security benefit. It may be available if people in need of care are unable to cover the necessary care costs from their own income, assets and long-term care insurance benefits. The social services department is usually responsible for this. The benefit may apply to both home care and residential care, but is particularly common where care home costs are high.
Applying for care support is emotionally draining for many families. Nobody likes applying for social security benefits, especially not after a long working life. Nevertheless, this benefit is designed precisely for situations where care costs exceed one’s own means. It is not a personal failure, but part of the social security system. The fact that you feel you have to include copies of half your life’s documents is yet another chapter in the story of human civilisation.
Before granting approval, the social services department assesses income and assets. In the case of married couples, the financial situation is assessed jointly. Maintenance claims against children may also be a factor under certain circumstances, although the income thresholds are now significantly higher than they used to be. Many adult children are therefore not automatically obliged to pay. Nevertheless, the specific situation should always be assessed on a case-by-case basis.
It is important to apply for care support in good time. Anyone who realises that the costs of a care home or outpatient care are no longer sustainable in the long term should not wait for months. Social security benefits often only come into effect from the date of application or once the social security authority has been notified. Seeking advice early on helps to prevent debt and provides clarity.
Private provision and personal contributions
As statutory long-term care insurance does not provide full cover, private provision plays an important role. This includes savings, private supplementary long-term care insurance, property planning, powers of attorney and a realistic assessment of future care needs. The need for long-term care is not a rare occurrence, but a risk that affects many people at some point in their lives. Nevertheless, it is often only discussed once the crisis is already upon us.
Private supplementary care insurance can help to cushion the impact of future co-payments. Depending on the policy, it pays a daily care allowance, covers certain costs or supplements the benefits provided by statutory care insurance. Such policies are particularly worthwhile if they are taken out early and remain affordable in the long term. Anyone who only looks for insurance cover once they start needing care will usually be disappointed. As is well known, insurance companies are particularly helpful as long as the risk has not yet materialised. A rather charming business model.
Savings are also important. They can be used to fund home modifications, personal contributions, short-term support or transitional periods. Families should discuss openly what funds are available and what the person concerned would like. This also includes a lasting power of attorney, a living will and a bank mandate. Without clear powers of attorney, even paying a bill can suddenly become a bureaucratic obstacle course.
Private provision is no substitute for state benefits, but it does complement them. The aim is not to foresee every eventuality perfectly. That is impossible. The aim is to remain able to make decisions when care becomes necessary. Sorting out financial and legal matters early on takes a considerable burden off relatives later on.
Tax relief on care costs
Care costs may have tax implications. Under certain conditions, expenses can be claimed as exceptional financial burdens, household-related services or a flat-rate care allowance. Which option is appropriate depends on the specific situation: Who is paying the costs? Where does the person in need of care live? Have they been assigned a care level? Are services being provided by relatives? Are there invoices and proof of payment?
Typical costs that may be relevant for tax purposes include outpatient care services, care home fees, domestic help, accessibility modifications, travel costs or certain care services. It is important to keep receipts carefully. Cash payments are often problematic because the tax office will want to see proof of payment. Bank transfers, invoices and statements of services are therefore much better.
The flat-rate care allowance may be of interest to relatives who provide care free of charge to someone in need of care. One of the requirements is that the person in question has a specific care level or a corresponding need for assistance. In case of doubt, the details should be checked with a tax adviser. Professional advice is particularly worthwhile where several relatives are involved or where high care home costs are incurred.
Tax relief is no substitute for care services, but it can reduce the annual financial burden. Many families overlook this point because they have enough other worries to deal with in the day-to-day reality of providing care. It’s understandable, but a shame. After all, the tax office rarely forgets anything – it’s a one-way street when it comes to remembering things.
KfW, state programmes and regional funding schemes
In addition to long-term care insurance, other funding schemes may be available, particularly for accessibility improvements and home adaptations. Depending on your household circumstances, KfW offers – or has offered – schemes for age-appropriate home modifications, burglary protection or measures to reduce barriers. As funding may be limited and schemes may be temporarily suspended, you should always check the current terms and conditions directly before signing any contracts or commissioning any work.
Federal states, local authorities and housing advice centres may also provide regional grants or advisory services. These schemes vary considerably. Some fund specific building alterations, whilst others support advisory services or provide low-interest loans. It is particularly worth doing some research before starting work on larger projects such as bathroom conversions, ramps, door widening or stairlifts.
The biggest mistake is to wait until the work has been completed before looking for funding. Many schemes require an application to be submitted before work begins. This means: first find out what’s available, then get quotes, then submit the application, then wait for approval, then commission the work. Yes, this sequence is a bit of a hassle. No, ignoring it won’t make it any cheaper.
A care or housing advisory service can help you sort through the various funding options. It is important to check whether grants from the long-term care insurance fund, regional programmes, KfW funding and tax relief can be combined. Not every combination is permitted, but costs can often be significantly reduced if you take a structured approach.
Common mistakes in applications
Many forms of financial assistance are not lost because people are not entitled to them. They are lost because applications are submitted too late, are incomplete or lack sufficient justification. This happens particularly often in relation to care levels, home adaptations, respite care, short-term care and support services. Anyone who doesn’t know the rules wastes time, money and nerves.
A common mistake is to paint too positive a picture of everyday care. Many of those affected want to appear independent, whilst relatives do not wish to dramatise the situation. This results in an application that paints a picture bearing little resemblance to reality. For the long-term care insurance fund, however, what counts is the actual need for support. If help is required with washing, getting dressed, eating, walking, remembering things, managing medication or dealing with restlessness at night, this must be clearly stated.
A second mistake is a lack of documentation. Without a care diary, doctors’ reports, hospital records, a medication schedule, diagnoses or photos of barriers in the home, the assessment becomes more difficult. This does not mean that every application has to be a novel. But it should clearly demonstrate why the benefit is necessary. Care insurance funds are not mind readers, even if some decisions sound as though they come from a parallel reality.
A third mistake is missing deadlines. Decisions should be checked immediately. If benefits are refused or approved at too low a rate, an appeal can be lodged. The deadline is stated in the decision. Anyone who is unsure should seek advice in good time. A well-reasoned appeal can make a big difference.
- Submit applications before the start of a project, if possible.
- To describe the reality of everyday care in a realistic and comprehensive manner.
- Check official notices and note the deadlines for lodging an appeal.
- Keep invoices, receipts and correspondence organised and in a safe place.
How families can plan for care costs in a practical way
Effective care funding starts with an assessment of the current situation. What limitations are there? What help is needed daily, weekly or only occasionally? Who is currently taking care of which tasks? What costs are already being incurred? Which benefits have been approved? Which applications are still pending? These questions may seem simple, but they help bring order to a situation that initially feels chaotic for many families.
The next step is to review existing entitlements. Has a care level been assigned? Is it still appropriate? Is care allowance being used? Are care benefits in kind appropriate? Is the respite care allowance being fully utilised? Is there an entitlement to care aids? Is the home safe? Is day care required? Does respite care need to be planned for? This review should be carried out regularly, as care needs change. What works in the spring may no longer be sufficient by the autumn.
This is followed by a financial overview. This includes pensions, income, savings, insurance, running costs and expected care costs. In the case of residential care, several care homes should be compared. In the case of home care, the services on offer should be explained clearly. For home modifications, cost estimates should be obtained and applications for funding submitted in advance.
It is helpful to have a central folder, either digital or on paper. This should contain your care level assessment, powers of attorney, medication schedule, medical reports, invoices, care contracts, correspondence with your care insurance provider, tax documents and funding approval notices. That sounds rather stuffy. It is, in fact, a bit stuffy. But when you need care, a good folder can sometimes be the difference between being able to take action and feeling overwhelmed by paperwork.
A comparison of funding options for home care, outpatient care and care homes
The right financing depends heavily on how care is organised. In the case of home care provided by relatives, the focus is on care allowance, respite care allowance, care aids and respite care. This combination can work well for a long time if care needs are moderate and relatives have sufficient resources. However, it reaches its limits when physical care becomes more demanding, dementia progresses or relatives themselves are under pressure due to work or health issues.
In the case of home care, the focus shifts to care benefits in kind and combined benefits. A care service takes on fixed assignments, whilst relatives supplement the care provided. The advantage lies in professional support. The disadvantage is that services are subject to a budget and any additional requests may have to be paid for privately. Precise scheduling is therefore important.
Semi-residential services such as day care provide relief without the person in need of care having to move out of their home entirely. They are particularly suitable when care is required during the day or when relatives are working. Residential care becomes necessary when safe care can no longer be provided at home. Financially, it is usually the most burdensome, as accommodation, meals and capital costs result in significant out-of-pocket expenses.
There is no one-size-fits-all solution. Good care funding is therefore not a one-off decision, but a process. Families should regularly check whether the current care arrangements are still safe, affordable and humane. After all, a solution that only works on paper is no solution at all. As we all know, paper doesn’t suffer from back pain, doesn’t work night shifts and doesn’t have a dementia diagnosis in the living room.
Advice: Why nobody should use this system on their own
Funding for care is complex because various systems are interlinked: long-term care insurance, health insurance, social security, tax law, housing support, private provision and regional schemes. Anyone trying to sort this out on their own, alongside work, family and the day-to-day demands of caregiving, should not be surprised if they feel overwhelmed. Seeking advice is therefore not a sign of ignorance, but a sensible shortcut through a system that was evidently designed by people with a deep-seated love of spreadsheets.
Long-term care insurance funds are obliged to provide advice. In addition, there are long-term care support centres, local authority advice centres, housing advice services, consumer advice centres and social welfare organisations. They can help you understand the benefits available, prepare applications, review appeals and find suitable providers. Advice is particularly valuable when it comes to home adaptations, care home costs or assistance with care.
Good advice should be independent, understandable and practical. It should not merely list what is theoretically possible, but show which steps make sense to take next. Families do not need a barrage of technical jargon, but a plan: Which benefit should we apply for first? Which documents are missing? What is the deadline? What costs remain outstanding? Who is responsible?
The sooner you seek advice, the better. In a crisis, decisions are often more expensive, more rushed and more emotionally stressful. Those who are prepared, on the other hand, can act more calmly and make better use of financial support.
FAQ: Frequently asked questions about financing and grants
Which feature is the most important?
The most important basis is the recognised care level. Without it, many benefits are not available, or are only available to a limited extent. The main benefit then depends on the type of care provided: care allowance for care provided by relatives, care benefits in kind for outpatient services, residential care subsidies in care homes, and home adaptations to remove barriers in the home.
Is care allowance subject to tax?
Care allowance is, in principle, a social security benefit for the person in need of care. If it is passed on to relatives, the tax treatment depends on the individual case, particularly where professional care is involved. If in doubt, tax advice should be sought.
Can you combine care allowance with care services?
Yes. The ‘combined benefit’ scheme allows care benefits in kind and a proportionate care allowance to be combined. This makes sense if an outpatient service takes on certain tasks whilst relatives continue to provide some of the care.
When should you apply for home adaptations?
Always before work begins. Estimates, photographs and a statement of reasons should be submitted with the application. Applications submitted retrospectively often cause problems.
What happens if care home fees cannot be paid?
If your income, assets and care insurance benefits are insufficient, you can apply to the social security office for care assistance. Your financial situation will be assessed. Advice is particularly important here.
Who can help with filling in the applications?
Long-term care insurance funds, care support centres, social welfare organisations, consumer advice centres and regional advice centres can provide support. In the event of appeals or complex social security issues, additional legal advice may be advisable.
Conclusion: Understand the grants available, make use of the services, and plan your care more effectively
Funding and grants often determine how well care can be organised in everyday life. Long-term care insurance provides important benefits, but it does not apply automatically and does not cover everything. That is why the care level, care allowance, care benefits in kind, respite allowance, home adaptations, care aids, short-term care, respite care, day care and funding for residential care must all be considered together.
By submitting applications early, checking decisions, combining benefits and seeking advice, you can significantly reduce the financial burden. At the same time, this takes the pressure off relatives and provides greater security for those in need of care. The most important step is not to treat care funding as a one-off formality, but as an ongoing planning process. Care needs change over time. Funding must adapt accordingly.
Ultimately, it’s not about loving every bit of red tape. Nobody should have to stoop that low. It’s about ensuring that existing entitlements are not neglected and organising care in such a way that people can be looked after with dignity, without families being overwhelmed financially and emotionally.